
Key Takeaways
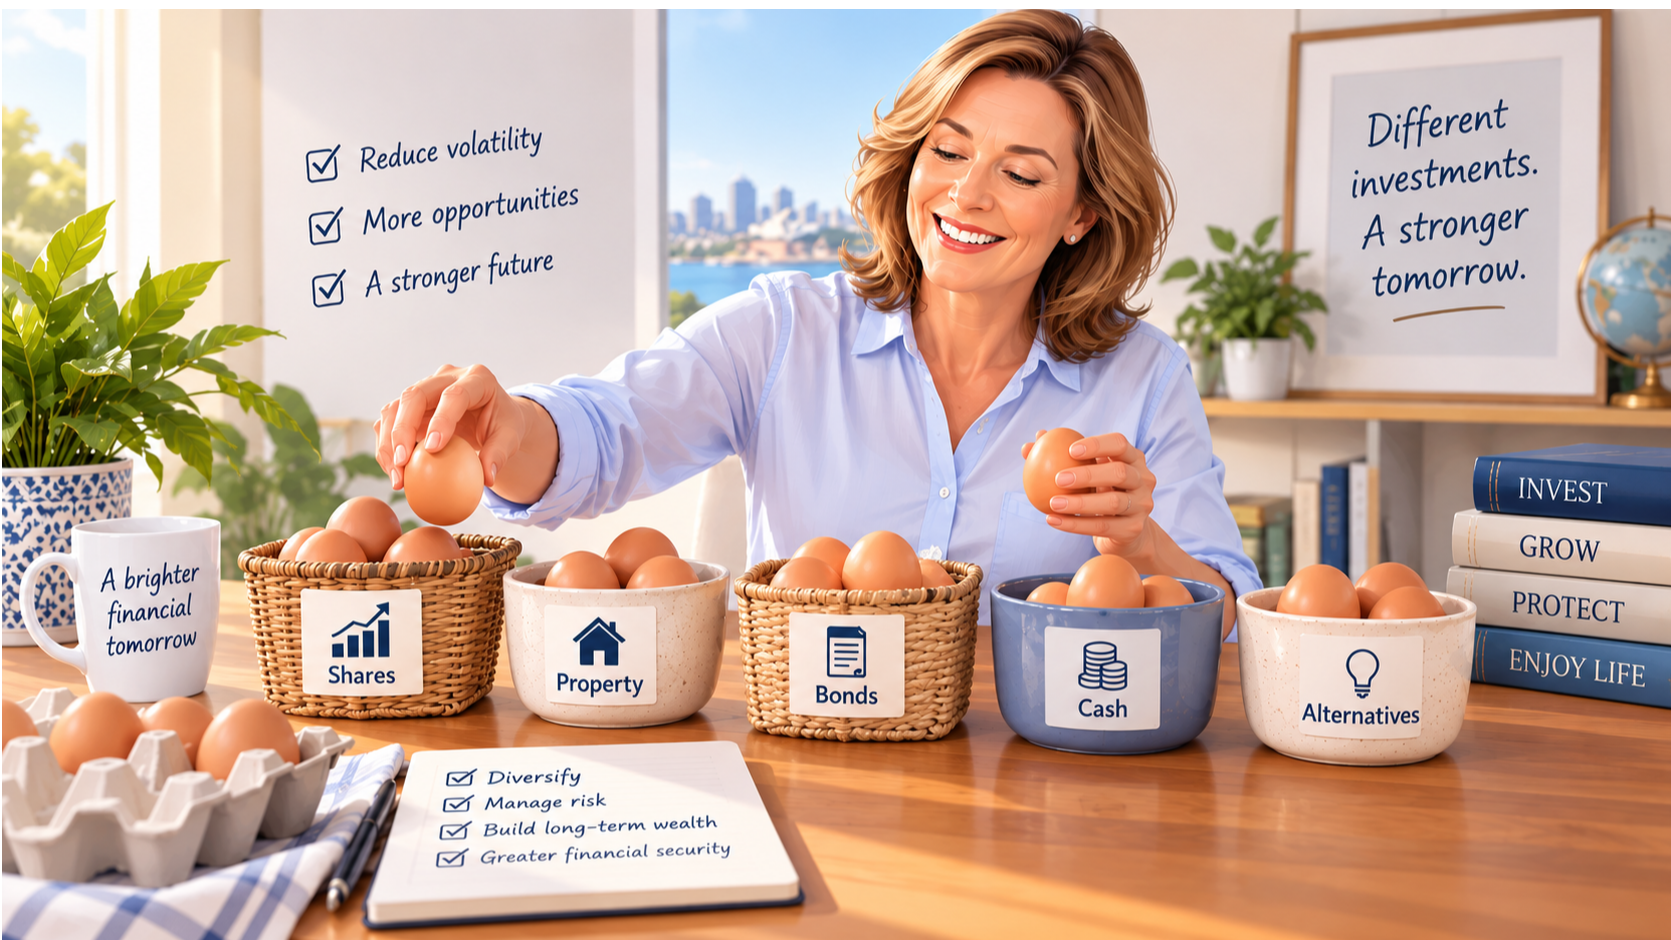
- Diversification spreads money across different types of investments so no single downturn can sink the whole portfolio
- Diversified portfolios tend to carry lower volatility than concentrated ones, which matters for anyone who cannot afford wild swings close to retirement
- Australian portfolios that lean too heavily on local shares and property can face added risk due to home bias, since the ASX 200 is itself concentrated in financials and resources
- Common asset classes for spreading risk include Australian and international shares, bonds and cash, property, and commodities such as gold
- Diversification reduces risk and volatility without necessarily giving up return, though it cannot remove every risk from a portfolio
Anyone who has watched their superannuation balance jump around during a rocky year on the share market has probably wondered whether there is a better way to invest. Diversification is often the first strategy financial professionals point to, but does spreading money around actually make a real difference, or is it just an old saying that sounds good on paper? For Western Australians over 45 and those closing in on retirement, the answer matters more than ever, since there is less time to recover from a bad run of losses.
Why Diversification Is Key to Managing Risk
Diversification means spreading investments across different asset types rather than betting everything on one sector, one company, or one country. The logic behind it is simple: not every part of the market moves in the same direction at the same time, so losses in one area can be offset by steadier or stronger performance elsewhere. This matters a great deal in Australia, where interest rates shift, commodity prices swing, and global events regularly ripple through local markets.
Approved Financial Planners points out that diversification is one of the few strategies that reliably reduces risk and volatility without necessarily sacrificing long-term returns. That is a rare combination in investing, where reducing risk usually comes at some cost to potential gains. Because Australian portfolios are often exposed to local swings in interest rates and global knock-on effects, building in a mix of assets helps smooth out the bumps and preserve capital when markets get choppy.
For someone approaching retirement, that smoothing effect carries real weight, since a sudden market drop shortly before retirement can permanently reduce the size of a nest egg when there is less time left to recover through future growth. Diversification reduces how hard a market fall hits, even though it cannot prevent markets from falling in the first place.
Why Different Assets Cushion Each Other’s Losses
The mechanism behind diversification comes down to correlation, which is simply a measure of how closely two investments move together. Shares, bonds, property, and commodities each respond differently to the same economic event, and that difference is what gives diversification its power.
When share markets tumble, bonds or gold sometimes hold steady or even rise, cushioning the overall portfolio. This does not happen every single time, but the tendency for different assets to zig while others zag is well documented, and it is the reason well-built portfolios blend growth assets with defensive ones. Research into diversified portfolios consistently shows they carry lower volatility than concentrated ones, which matters a great deal for someone who cannot afford wild swings in the years leading into retirement.
Key Asset Classes for Australian Investors
Building a diversified portfolio means understanding the role each major asset class plays. None of them work in isolation, and each brings a different mix of growth potential, income, and protection during downturns.
Australian and International Shares
Shares are usually the engine room of long-term growth in a portfolio, and Australian investors often start close to home with ASX-listed companies. There is good reason for familiarity, since franking credits and dividend income make local shares attractive. However, the Australian share market is heavily weighted toward financials and resources, which means a portfolio built only on ASX shares can be vulnerable if those sectors have a bad run.
Adding international shares helps balance this out. Exposure to global businesses across the United States, Asia, and emerging markets gives a portfolio access to industries barely represented on the ASX, such as large-scale technology and healthcare innovation. It also reduces reliance on the Australian economic cycle alone, spreading growth potential across multiple regions and industries.
Bonds, Fixed Income and Cash
Bonds and fixed income investments act as the defensive backbone of a portfolio. They typically produce steadier, more predictable income than shares, and they often behave differently during downturns, sometimes rising in value when share markets fall. Term deposits and government bonds fall into this category, along with corporate bonds that carry slightly more risk but usually offer a bit more return.
Cash and cash equivalents sit at the safest end of the spectrum. Returns are modest, but the stability and liquidity they provide are valuable, particularly for covering short-term needs or acting as a buffer during volatile periods. Superannuation funds typically hold a slice of cash and fixed income for exactly this reason, using it to dampen large swings in overall fund value.
Property, Gold and Commodities
Property, whether held directly or through listed vehicles like real estate investment trusts, adds another layer of diversification. It often generates steady income and can offer some protection against inflation, though property cycles do not always move in step with shares or bonds.
Gold and other commodities round out the picture. Gold in particular has a track record of behaving quite differently from shares and bonds, often holding its value or even climbing when other assets fall. This low correlation with mainstream financial assets is why gold is frequently included as a hedge against inflation, currency swings, or broader market stress.
Putting Diversification Into Practice
Knowing the theory is one thing; building a portfolio that actually reflects it is another. A few practical habits make the difference between genuine diversification and a portfolio that only looks diversified on the surface.
- Set clear objectives first, including what the money is for, when it will be needed, and how much risk can genuinely be tolerated.
Diversify within asset classes and across them, spreading share investments by geography and sector rather than clustering in one or two industries.
- Include defensive assets such as bonds, cash, and possibly gold, even though their returns are lower, because they help protect capital during downturns.
- Favour low-cost vehicles such as index funds and exchange-traded funds where appropriate, since fees compound over time and quietly erode returns.
- Rebalance regularly, trimming assets that have grown beyond their target weighting and topping up those that have lagged, so the portfolio does not drift toward unintended risk.
- Review the strategy periodically, since risk tolerance naturally shifts with age, changing circumstances, and proximity to retirement.
Multi-asset funds, index funds, and increasingly alternative or private assets are common tools for putting these ideas into action, with each providing a different balance of cost, control, and complexity.
Where a Financial Planner Adds Value
Building a genuinely diversified portfolio takes more than picking a handful of different investments and hoping for the best. A financial planner’s role starts with understanding risk tolerance and time horizon, working out how much loss someone can realistically absorb versus how much volatility they can stomach emotionally, and how far away they are from needing the money.
From there, a planner constructs an asset allocation suited to that profile and keeps it on track through regular rebalancing, since markets rarely move in a way that keeps a portfolio’s original weightings intact. Planners also keep an eye on the less glamorous but equally significant details: monitoring fees, managing tax implications such as capital gains and franking credits, and helping investors avoid behavioural traps like panic selling during a downturn or chasing last year’s best-performing asset. These ongoing checks are often where the real value of professional advice shows up, particularly for investors juggling superannuation, personal investments, and retirement planning all at once.
Mistakes That Undermine Diversification
Even well-intentioned diversification can go wrong. A few recurring mistakes tend to undo the benefits investors are hoping to gain.
Over-Diversification and Rising Fees
There is such a thing as too much diversification, sometimes referred to as “diworsification.” This happens when an investor keeps adding funds, shares, or products that overlap heavily with what they already hold, without meaningfully improving the balance between risk and return. The result is unnecessary complexity and, often, higher fees, since every additional fund or product typically comes with its own cost. Adding a tenth international share fund when nine similar ones are already held rarely adds protection; it just adds paperwork and expense.
Home Bias and Correlation Breakdown in Crises
Australian investors commonly lean heavily toward domestic shares and property, a pattern known as home bias. It feels natural to invest close to home, but it also means a portfolio can be overly exposed to the ups and downs of the Australian economy specifically. Given how concentrated the ASX 200 is in financials and resources, this bias can leave a portfolio more fragile than it appears.
There is also a subtler risk worth understanding: correlations between assets can shift during a crisis. Assets that normally move independently sometimes start falling together when markets are under extreme stress, as seen during major global downturns. This does not mean diversification stops working, but it is a reminder that no combination of assets provides a perfect safety net in every possible scenario.
Diversification Reduces Risk, Not Eliminates It
Diversification remains one of the most dependable tools for managing investment risk, particularly for those with less time to ride out a downturn before retirement. It smooths volatility, cushions losses, and helps preserve capital through the inevitable ups and downs of markets. What it does not do is remove risk altogether. Systemic shocks, sequence of returns risk for those drawing down retirement income, and simple human error in reacting to market noise can still affect outcomes no matter how well a portfolio is built.
Understanding this distinction separates realistic expectations from false confidence. Diversification manages the odds so that no single event can do disproportionate damage to a life’s worth of savings, without guaranteeing against loss. For those wanting to see how a balanced mix of Australian shares, international shares, bonds, property, and commodities might apply to their own circumstances, working through a properly structured diversification strategy is a sensible next step toward steadier, more resilient retirement planning.
Before making any significant financial decisions, seek advice from a licensed professional.
Approved Financial Planners Pty Ltd
7/437 Cambridge St,
Floreat
WA
6014
Australia


